WEEKLY MARKET SUMMARY
Global Equities: Stocks rebounded sharply this week even as turmoil engulfed Nvidia (NVDA) and sparked industry-wide AI concerns. The company opened an investigation into reports that CEO Jensen Huang had been the target of a foreign intelligence effort, after Huang admitted to an extramarital affair with a woman suspected of being a Chinese spy, and the shares fell -9.5% across Monday and Tuesday. Later in the week, reports of a second affair with an Nvidia executive sent the stock sharply lower, and on Thursday the board announced Huang’s resignation, naming CFO Colette Kress interim CEO. Nvidia’s market value has dropped by about $1 trillion since the first reports surfaced on October 29. For the week, the S&P 500 rose 2.5%, the Nasdaq gained 2.3%, the Dow finished 2.2% higher. Small caps were also positive despite expectations for higher interest rates, with the Russell 2000 gaining 1.4%. Overseas, European stocks benefited from the rotation out of US technology. Developed Markets ended the week up 2.2%, while Emerging Markets gained 2.7%.
Fixed Income: Treasuries sold off sharply after hot inflation data and hawkish Fed commentary. Fed Governor Christopher Waller said a half-point hike in December should be on the table if core CPI came in around 0.3%, which it did, while Dallas Fed President Lorie Logan said the Fed needs at least two more quarter-point hikes. The 10-year yield rose 28 basis points to 5.14%, and the 30-year reached 5.47%. Markets now fully price a rate hike at the December 8-9th meeting, up from about 77% a week ago, with around an 11% probability of a half-point move.
Commodities: Oil prices fell early in the week before rebounding on Thursday after President Trump said the US does not need a deal with Iran, raising concerns that the conflict will continue. WTI ended the week around $88.77, and Brent rose to $95.95, with reports of additional attacks on Saudi energy infrastructure adding to supply concerns. Gold gave back much of last week’s rebound as rising Treasury yields and a stronger dollar weighed on the metal. Gold fell to its lowest level in over a year, ending the week at $3,888 per ounce.
WEEKLY ECONOMIC SUMMARY
Consumer Price Inflation Runs Hot: The Consumer Price Index (CPI) rose 0.4% in October, above the 0.3% forecast, after a 0.6% gain in September. Core CPI, which excludes food and energy, rose 0.3%, above the 0.2% forecast and matching the pace of August and September. Food prices rose 0.5%, energy 0.7%, and shelter 0.3%. Year-over-year figures were not published because October 2025 data were never collected during the government shutdown. Fed Vice Chair for Supervision Michelle Bowman estimated core PCE inflation, the Fed’s preferred measure, likely rose to 3.3% over the 12 months to October.
Producer Prices Cool: The Producer Price Index rose 0.3% in October, below the 0.4% expected, but the gain was offset by an upward revision of 0.1% in the September data from 1.3% to 1.4%. Core producer prices rose 0.3%, in line with forecasts. Producer prices were up 6.5% from a year earlier, the largest annual increase since November 2022. While energy costs cooled from September’s 10% spike, food price inflation accelerated, which can be attributed to the higher energy costs of transportation and refrigeration. Friday’s report was the last CPI or PPI release before the Fed’s December 9th decision.
Earnings Update: AI infrastructure results were strong this week, softening the blow from the Nvidia fallout. CoreWeave (CRWV) reported a 168% increase in quarterly revenue and raised its 2026 guidance, sending shares up about 25% on Wednesday before they gave back roughly 8% on Thursday. Applied Materials (AMAT) reported beat on both earnings and revenue, but shares dipped slightly after rallying 24% over the prior four sessions. Cisco (CSCO) provided increased guidance and beat estimates, but shares slipped roughly -6% Friday. Cerebras (CBRS) reported record revenue of $210.8 million and raised its outlook, propelling shares by roughly 10% Friday.
The Week Ahead: All eyes turn to Nvidia (NVDA), which reports third quarter results Tuesday after the close in its first report since Huang’s departure. Consensus earnings estimates already sit above the top of the company’s own guidance range, and options markets imply a move of roughly 7.7%. Investors will look for clarity on data center demand, margins and the search for a permanent CEO. Retail earnings also take focus, with Home Depot (HD) on Tuesday, Target (TGT), Lowe’s (LOW) and TJX (TJX) on Wednesday, and Walmart (WMT) on Thursday. The Fed releases minutes from its October meeting on Wednesday, and Fed Chair Kevin Warsh speaks on Monday.
CHART OF THE DAY
The Chart of the Day looks at how the AI trade held up as Nvidia (NVDA), its largest and most influential company, went through a leadership crisis. Nvidia fell -12.8% for the week after reports of CEO Jensen Huang’s personal conduct led to his resignation on Thursday. Based on the weekly performance of Nvidia’s suppliers and competitors, investors treated the scandal as a company-specific issue rather than a reason to question AI spending. Chip competitors led the gains, with AMD up 18.9% and Broadcom up 18.2%, as investors looked for alternative sources of AI computing power. Suppliers also rallied, led by Micron and Lam Research, each up nearly 13%, a sign that demand for the memory and equipment behind AI data centers remains strong regardless of whose chips win. The hyperscalers building their own chips posted more modest moves, likely because they are also among Nvidia’s largest customers. Nvidia’s earnings on Tuesday will be the next test of whether the fallout stays contained.
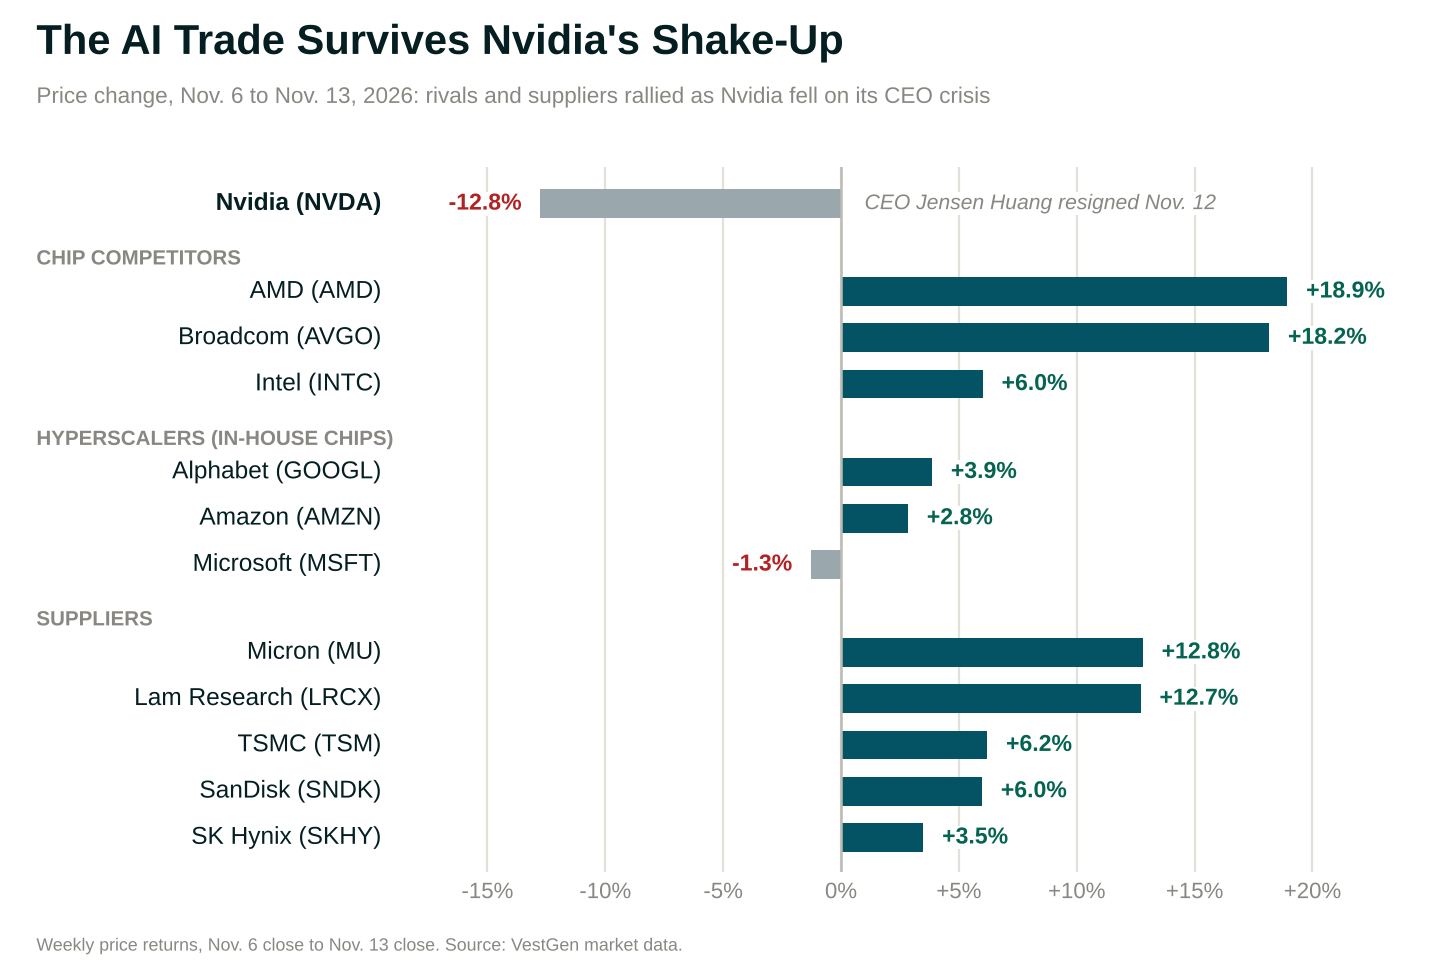
Chart and commentary by VestGen Investment Management.